

Federal Tax Expenditures
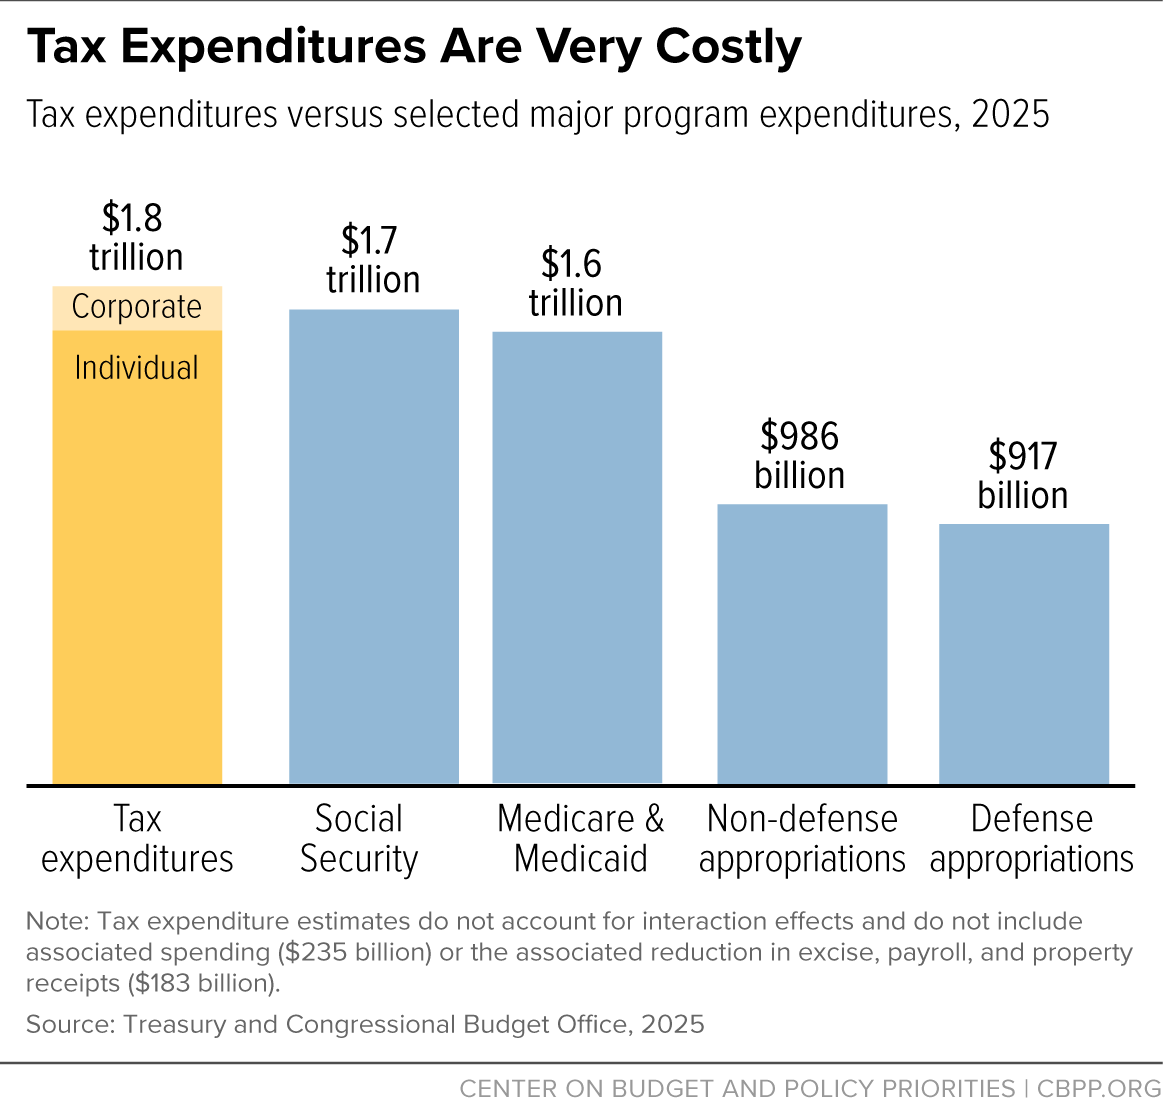
“Tax expenditures” are subsidies delivered through the tax code as deductions, exclusions, and other tax preferences. In fiscal year 2025, tax expenditures reduced federal income tax revenue by an estimated $1.75 trillion, and they reduced payroll taxes and other revenue by an additional $183 billion.
Tax expenditures reduce the amount of tax that households or corporations owe. To benefit from a tax expenditure, a taxpayer must undertake certain actions or meet certain criteria. For example, some households that have a mortgage can reduce their taxes by claiming a tax deduction for their spending on mortgage interest, and corporations can receive a tax subsidy for investing in machinery.
Tax expenditures are costly. For comparison, taken together, all federal income tax expenditures cost more than Social Security, the combined cost of Medicare and Medicaid, or the cost of either annually appropriated defense or non-defense spending. (See first chart, below.)
The largest individual income tax expenditure in 2025 was the provision that lets households exclude from taxable income the value of employer-provided health insurance. The next three largest were the exclusion of tax breaks on owner-occupied housing (a subsidy for homeowners), the exclusion for employer-based retirement plans, and the lower rates at which capital gains are taxed relative to earned income.
The largest corporate tax expenditures for 2025 included the 2017 tax law’s lower tax rates on much of U.S. multinational corporations’ foreign income (relative to the rates that they face on their domestic profits) and the credit for increasing domestic research activities, commonly known as the Research & Development (R&D) Tax Credit.
2017 Tax Law, 2025 Republican Reconciliation Law Made Significant Changes to Tax Expenditures
The 2017 tax law reshaped tax expenditures in important ways, in some cases limiting tax expenditures while expanding or creating others.
The law restricted several specific itemized deductions, including by capping deductions for state and local taxes at $10,000 and reducing the mortgage interest deduction from interest on up to $1 million in loan principal to $750,000 for new mortgages. As a result of these changes, combined with the law nearly doubling the standard deduction, from $6,500 to $12,000 for single filers and from $13,000 to $24,000 for married couples filing jointly, the share of filers who itemized deductions fell from 31 percent in 2017 to less than 10 percent by 2022. The total dollar value of itemized deductions claimed nationwide fell by more than half, from $1.4 trillion to $668 billion, over the same period.
But the 2017 law also expanded or created new tax expenditures, particularly for large corporations or other profitable businesses. For example, it created a 20 percent deduction for certain income that owners of pass-through businesses (partnerships, S corporations, and sole proprietorships) report on their individual income tax returns, which previously was generally taxed at the same rates as wage and salary income. This deduction is costly ($70 billion in 2025) and highly skewed to high-income households: around half of its benefits went to households with more than $1 million in income in 2024, according to the congressional Joint Committee on Taxation (JCT).

The 2017 law also enacted “full expensing,” which allows businesses to reduce their tax liabilities by deducting the full costs of investments immediately rather than over a number of years, and created a new, lower tax rate on multinational corporations’ overseas profits.
Moreover, the 2017 tax law left entirely untouched two of the largest individual tax expenditures in the tax code: the exclusion for employer-provided health insurance, which Treasury estimates will cost $296 billion in 2026, and the exclusion for employer-based retirement plans, which costs $156 billion. Both operate outside the itemized deduction system, so the standard deduction increase did nothing to limit their scope.
The 2025 reconciliation law largely continued the 2017 tax law’s approach. The law made the higher standard deduction and the restrictions on itemized deductions permanent. But it raised the state and local tax deduction cap from $10,000 to $40,000 through 2029 for most households (with a phaseout for those with incomes above $500,000), a change that will primarily benefit higher-income households. The reconciliation law also made permanent the 20 percent pass-through deduction and other corporate tax breaks like full expensing, while largely retaining the 2017 law’s low international tax rates. Both laws increased the Child Tax Credit, doubling it in 2017 and increasing it more modestly in 2025, but these increases left out most low-income families from any benefit.
The reconciliation law also added new temporary tax expenditures, including a deduction for certain tip and overtime income and an enhanced standard deduction for seniors. These deductions add to the law’s cost and do not adequately direct benefits to lower-income households.
Spending Through the Tax Code
Policymakers enact tax expenditures to promote certain policy goals. The distinction between these tax breaks and spending is often artificial and without economic basis.
Education is one example. On the spending side of the budget, the federal government provides Pell Grants to help low- and moderate-income students afford college. On the tax side of the budget, funds used to meet college expenses can grow tax free in special college savings accounts. Both of these policies are subsidies intended to make higher education more affordable, and although the government categorizes them differently, they are both a type of government spending.
Child care is another example. On the spending side of the budget, the government gives some households a subsidy for their child care costs through a spending program (the Child Care Development Fund). It also gives a tax credit for child care to some families, which is another form of spending to subsidize child care costs.
Similarly, business tax breaks targeted at specific industries, such as tax breaks for oil and gas corporations, are the equivalent of subsidy programs for those industries.
In general, any tax filer — whether individual or corporate — that meets the requirements for a tax break can receive it. This feature makes tax expenditures similar to programs where all people meeting eligibility criteria can receive benefits, such as Social Security or Medicare. The JCT and Congressional Budget Office have noted this similarity.
Policymakers also eliminate tax expenditures to inhibit a policy goal they disagree with, such as the $500 billion in clean energy tax incentives that the 2025 reconciliation law eliminated.
Tax Expenditures Are Tilted Toward Higher-Income Earners
The bulk of each year’s spending on individual tax expenditures is delivered through tax deductions, exemptions, or exclusions. The value of these tax breaks increases as household income rises: tax filers pay a higher marginal tax rate as their income moves them into a higher tax bracket, resulting in a greater benefit for each dollar that is deducted, exempted, or excluded.
The lower tax rates applied to long-term capital gains and qualified dividends and the deduction for state and local taxes are among the provisions of the tax code that operate this way. Capital gains are taxed at lower rates than traditional income or wages. In practice, this means that the gains earned from investments, such as the increase in a home’s value when it is sold, the appreciation of stocks held over time, or returns from other financial assets, are taxed less than income earned through work.

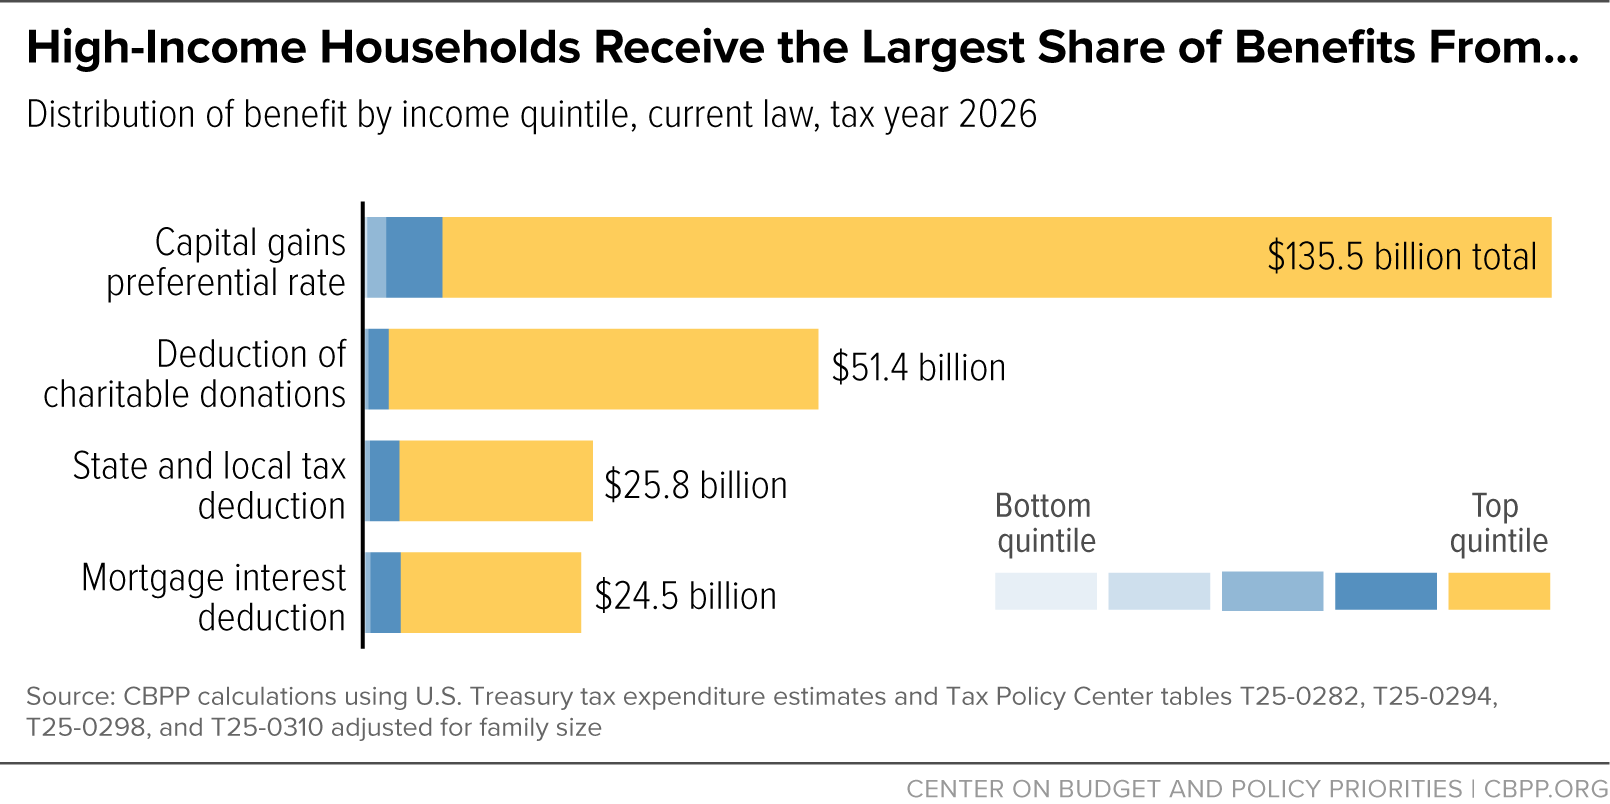
The deduction for state and local taxes functions differently but passes on benefits in a similar fashion. It lets itemizing taxpayers subtract certain state and local income, sales, and property taxes from their federal taxable income.
Both provisions reduce federal revenue by excluding significant portions of income from ordinary tax treatment. Because the value of these preferences rise as income and tax liabilities increase, their dollar benefits grow with household income. As a result, they deliver a larger share of their total benefits to taxpayers with higher earnings or greater investment income, even though these individuals are least likely to need financial incentives to engage in the activities that tax expenditures are generally designed to promote, such as buying a home, sending a child to college, or saving for retirement. Meanwhile, families with low and moderate incomes receive considerably smaller tax expenditure benefits for engaging in these activities. (See second chart, above.)
This also means that tax expenditures that favor higher-income people likely increase racial disparities in income and wealth. Racial barriers to economic opportunity erected by policy choices and private discrimination have resulted in households of color being disproportionately low or moderate income, so they receive much smaller benefits from many of these tax breaks, and in some cases are locked out of them altogether.
White households receive 92 percent of the total benefits from the preferential tax rate on capital gains and more than 80 cents of every dollar from deductions for mortgage interest and charitable contributions. The legacy of racial barriers and continuing discrimination (such as discrimination in housing and lending markets) also means that even among households with the same incomes, white households on average may be more likely to be able to claim these tax breaks and to secure a larger benefit from them than households of color.
Notable exceptions are tax credits, such as the Earned Income Tax Credit and the Child Tax Credit, which can be received in whole or in part as a tax refund by households whose incomes are too low to owe much federal income tax. These tax credits reduce poverty and raise the after-tax incomes of families in low-paying jobs, and also help reduce racial and gender inequities. To the extent that a credit brings a tax filer’s income tax liability below zero — i.e., to the extent the tax credit is refundable — federal budget accounting treats those costs as increased outlays rather than reduced revenue and so are not included in the tax expenditure figures in this analysis. But this accounting convention reinforces that tax expenditures and regular budget expenditures can each be thought of as “spending.”
Limiting Tax Expenditures Increases Income Subject to Tax
Many policymakers have proposed cutting or overhauling tax expenditures to reduce the deficit, increase investments made on the spending side of the budget, reduce tax rates, better target the breaks toward households that need the most help to engage in whatever activity the breaks are intended to promote, or a combination of those aims. Tax expenditures lose revenue because they shrink the “tax base” — that is, they reduce the amount of income that is subject to tax. That means scaling back tax expenditures raises revenue by increasing the size of the tax base, so it is often called “base broadening.”